Some people enjoy the process of making a spending plan or budget. They enjoy using spreadsheets to track their income and listing out all their expenses. They like the discipline and accountability.
But many people don't enjoy that structure. They may be wondering, "What's the point".
What's the point of budgeting?
It's actually pretty simple, Imagine a squirrel putting away acorns for winter. In a nutshell, that's why we budget.
Instead of saving for winter, we're saving for the future while making sure we have enough for today. We make a budget so we don't forget about putting aside money for later, when we are no longer working. What about our income and expenses? What about slicing and dicing so we have money to eat out, go to the movies, pay for our kid’s college and pay down debt?
To guide your spending, most of us need some type of budget. But if you feel overwhelmed and you want to streamline it as much as possible, you can use the principles of budgeting to be sure you're saving enough for long term goals like retirement. Then you can spend the rest.
Save for immediate and future needs.
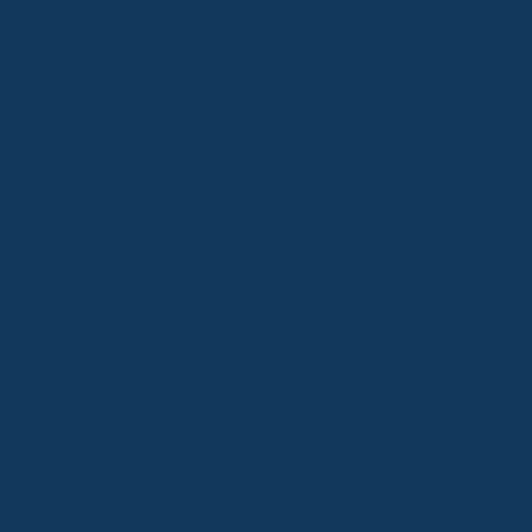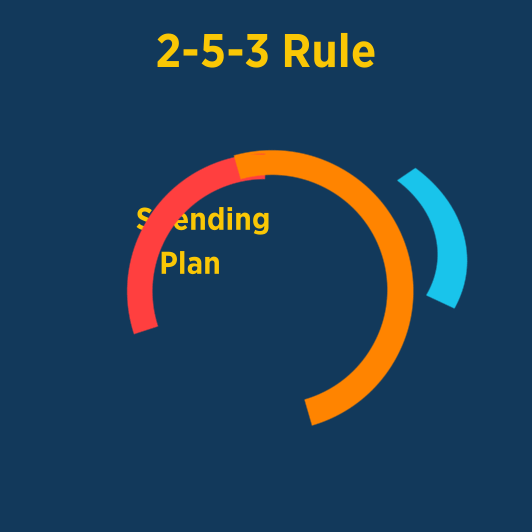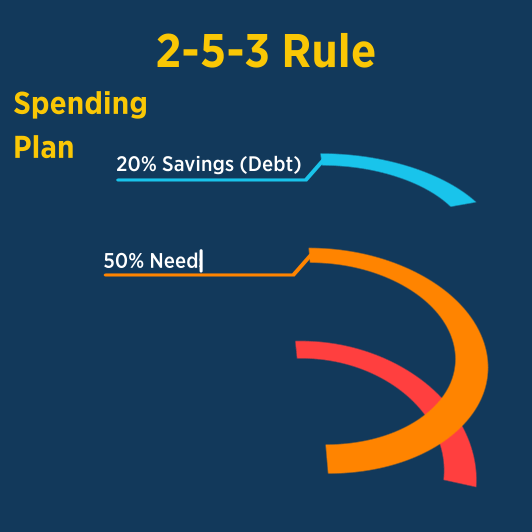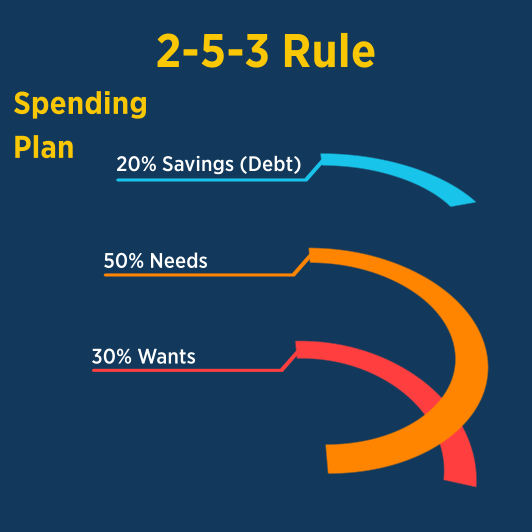
A lot of people don't like budgets, but they still want to be sure they're saving enough for future financial needs, such as retirement or for an emergency fund. For the budget wary, the 20-50-30 rule, a general spending plan framework. The 20-50-30 rule means that 20% goes to savings or paying down debt, 50% of your money goes to needs, and 30% goes to wants.
In the interest of keeping things simple, consider Jackie, a recent college graduate fortunate enough to enter the job market with no debt. She just landed a job that pays $50,000 a year.
Of course, starting with a blank slate is not realistic but it helps us illustrate the point, and once you get the point, you can apply it to different scenarios.
Jackie's first move should be saving for emergencies and retirement. And according to the 20-50-30 rule, she should put 20% or about $833 per month away.
That means some of the $833 can go to her employer-provided retirement savings plan — such as a 401(k), Thrift Savings Plan or 403(b), especially if she's eligible to receive matching contributions. Jackie should ask her employer to automatically deposit that money into her retirement plan account, so she never sees it hit her checking account. The other portion can go into an emergency savings fund, which can be automatically deposited into a dedicated savings account.
Be sure your needs are met.
If you're like Jackie and you're already saving 20% of your paycheck, take a minute to congratulate yourself. You've become one with that squirrel, and you haven't even had to put pen to paper.
Since you're on a roll, let's keep going. In the 20-50-30 rule, 50% of your income goes toward needs, which include all your essential expenses.
With Jackie's $50,000 salary, she has about $2,000 a month to spend on essentials. Essentials include expenses like mortgage or rent, utilities, property taxes, groceries, car payments, and gas.
Then have some fun — now and later.
Now for the fun part! The 20-50-30 rule allows 30% of your money to go toward things you want.
If you're already socking money away for needs like retirement and you're covering your essential living expenses, everything else is yours to spend guilt-free.
You probably don't need help coming up with items for your wants bucket, but it includes things you could live without, such as club memberships, dining out, streaming services, etc.
As you spend money on the fun stuff, consider setting some aside for more fun later. If you start saving now for your summer vacation or holiday gifts, you'll feel a lot more festive once these occasions arrive — not to mention after they're over.